
Bookkeeper QuickBooks ProAdvisorClose the month you still have open
We keep the books, close the month to the bank, and set payroll up. The return is next, and Steven Palmieri, a Tax CFO, writes it only after that close. This is the right page.
Name the month that is stuck

You will be talking to the Steven Palmieri practice.
The Tax CFO way through the month.
We keep the books in the program you already run. The Tax CFO closes the month to the bank and then reads it with you: your pay, the quarterlies, the return before April. A directory title can sit on a profile. The closed month tells you where the company is going.
Start with the open month
A result is not a method
People ask for a guaranteed outcome. We can show the test a month has to pass.
Click to see the test ›Tap to see the test ›
Two lists on the table
One list names the reports left unsigned. Matching, payroll setup, and the return fill the longer list.
Click to read both lists ›Tap to read both lists ›
The month has to match
The software can download the bank. Someone still has to say the difference is zero.
Click to see the match ›Tap to see the match ›
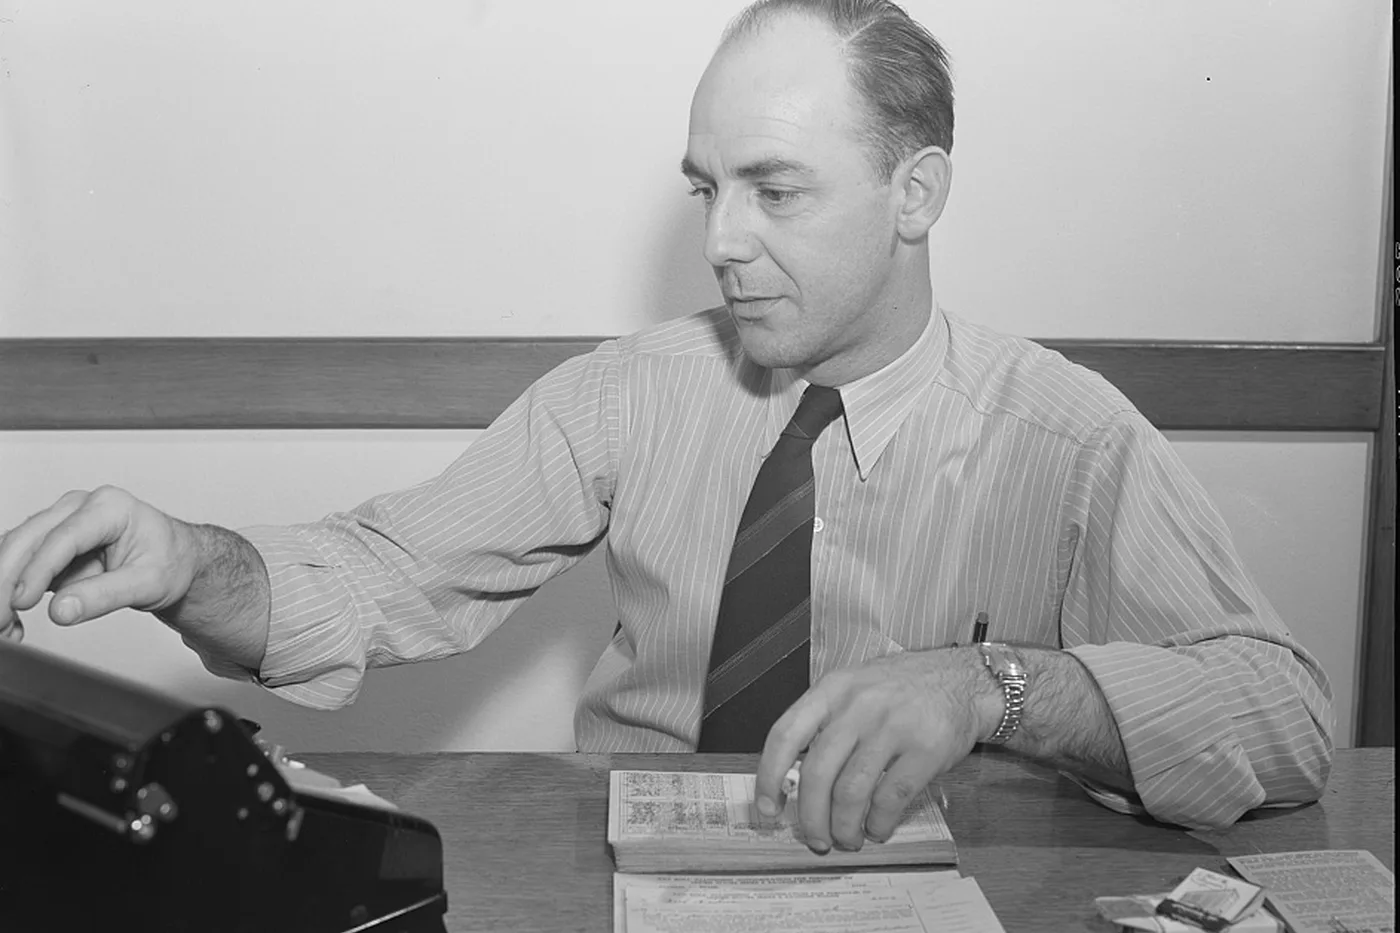
Payday stays with you
Setup can live here. The morning you send pay is still yours.
Click to see payday ›Tap to see payday ›
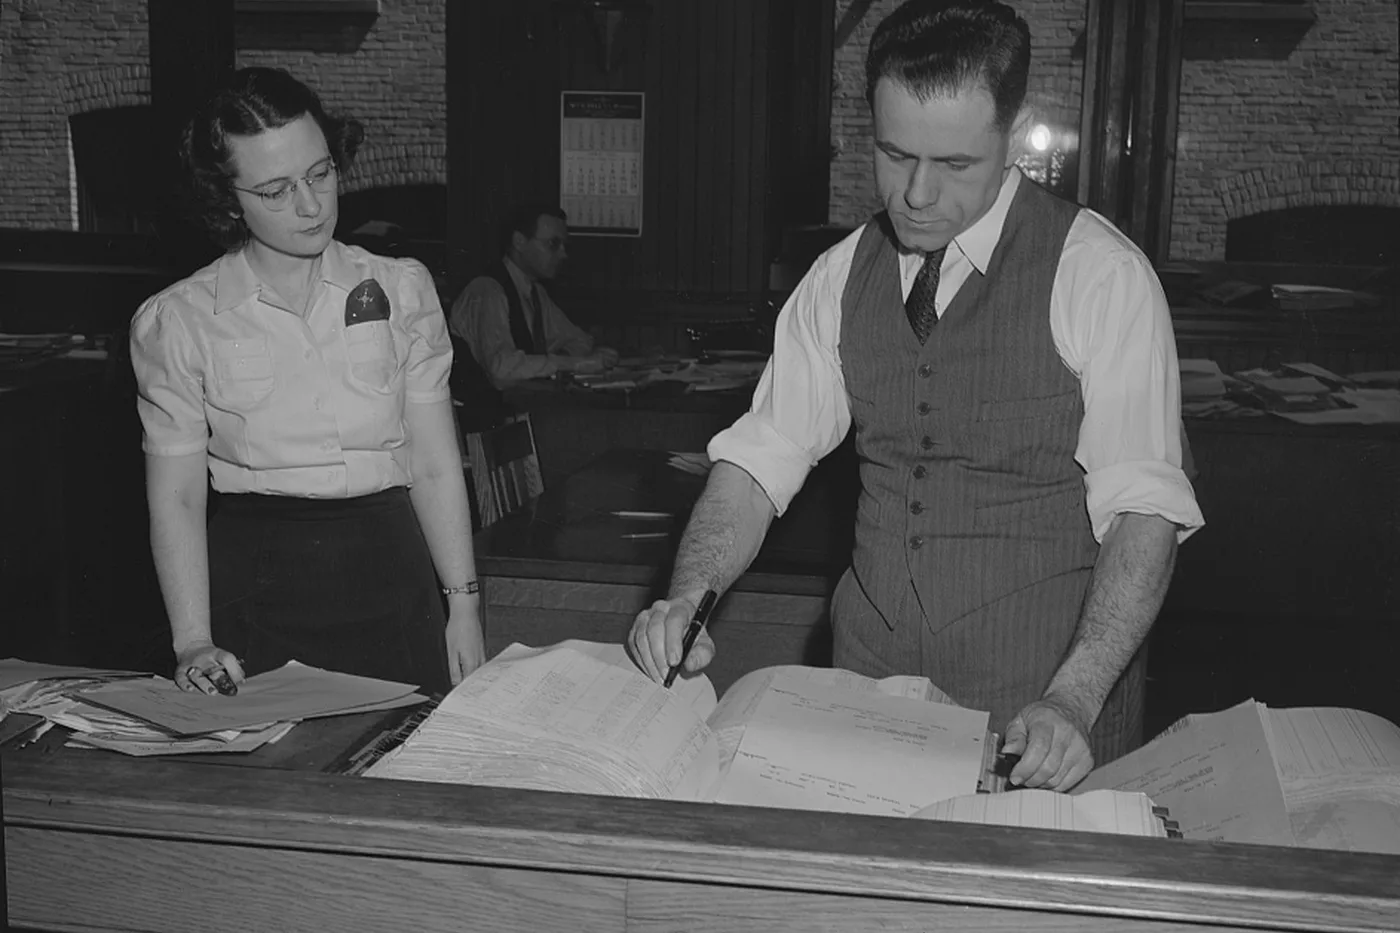
October can still move
By October most months can be closed, and the return is not drafted yet.
Click to see October ›Tap to see October ›
Bring the open month
Pick a time. We will look at one month that does not yet match the bank.
Click to pick a time ›Tap to pick a time ›
Six parts of a closed month
Five parts of the month are already named. The empty box is the signature we do not make.
Directory listThe software companyHere
The company that sells the software keeps the public list. A name on that list is their record, not a month we closed.
Bank matchThe closeHere
We tie the register to the statement. A month with a leftover difference stays open.
Payday setupYou still run itHere
The wage items and the state registrations are prepared on this side of the work. You and the provider already paying people still send the cycle.
StatementsFor the ownerHere
Once the month matches, the statements are readable. They are for you, and for anyone you later choose to show.
The returnFrom closed monthsHere
The return starts from months that have stopped moving. An open month is not a figure we will file.
A signatureOn a formal reportMissing
The signature is missing on purpose.
Steven Palmieri.
Tax CFO and the Entrepreneur's CFO. The public list can carry a name. The work on this site is the month that matches the bank, payroll set up while you still send payday, and a return built only from months that have stopped moving.
A name on a list is not a closed month
Unfold this part
Owners arrive after typing a directory title into a search box. The title belongs to the company that sells the software. That company decides who appears on the list, what the profile says, and which mark a listed person may show. None of that activity ties a bank statement to a register.
What the owner actually needs is narrower. A month either agrees with the bank or it does not. Payroll can be set up so the items and the registrations exist, and the owner still presses send on payday. Statements can be read by a person who was not in the software all month. The return can be prepared from those months, and only from those months.
This practice does that work. We do not join the company's directory from these pages, and we do not wear the program mark the company gives out. The address of the site uses the words people type. The pages underneath talk about the month.
A profile on that list is a record the software company keeps. When the month is open and you want it closed, the form on this page is the right one. We look at the statement and the register for the month you name.
How a bank match actually ends
Unfold this part
The feed brings in what the bank already knows. Each line then has to be matched to something the company did, or added because the company has not recorded it yet, or left as a question. A rule that guesses the category is a convenience. It is not the close. The close is the moment the register and the statement show the same figure on the statement date.
The leftover amount is written down before anyone calls the month finished. A leftover amount, even a small one, means a line is still missing or a line was recorded twice. Hiding it inside a plug account makes the next month harder, and it makes the return a guess.
The same pass catches transfers. Money that moved between the company's own accounts is not a sale and not an expense. If both sides are not marked, the profit is invented. We look for the pair.
A zero difference is the moment that month is allowed to stop. Later corrections are written as their own entries, in the month we find them, with a note about which month they belong to. We do not quietly reopen a finished month to make a report look smoother.
A deposit is not automatically a sale
Unfold this part
The bank feed is honest about the dollars and silent about the reason. A deposit can be a customer. It can also be the owner moving personal money in, a transfer from a savings account, a refund from a vendor, or a payout that has nothing to do with the shop. If all of those land in sales, the year is louder than the work.
We trace the payer before the line is called income. The owner's own name, a transfer from an account we already track, and a payout from a source that is not a customer come out of sales. The dollars stay on the books. The category changes.
Unidentified deposits do not sit in a parking spot through the return. A clearing account is allowed while we ask. It is not allowed as the answer. By the time a month is closed, that account is empty or the line is labeled with the question still open and kept out of sales until the answer arrives.
This is ordinary care. It is also the difference between a year a lender can read and a year that has to be rebuilt in the spring.
Clearing accounts have to empty out
Unfold this part
Every file grows a few accounts whose only job is to hold a question. Undeposited funds, a suspense account, an ask-me-later bucket. They are useful on a Tuesday. They are a problem if they still hold a balance on the day we call the month closed.
The cleanup is a list, not a speech. Each line gets a home: a sale, a transfer, an owner movement, an expense, or a refund. Lines we cannot place stay visible as open questions, and the month is not described as finished.
We do not sweep the leftovers into other expenses so the balance sheet looks tidy. That sweep is how a return inherits a number nobody can explain. The temporary account goes to zero because every line moved, or the month stays open because one line did not.
Owners can see the list. We would rather show three lines still waiting than a clean page that hides them.
Checks that never came back
Unfold this part
A reconciliation that ignores old outstanding checks will balance on the screen and lie on the paper. The check was recorded. The bank has not paid it. Until it is voided, reissued, or still expected, it belongs on the list.
We age that list. A check from last week is normal. A check from many months ago needs a decision written next to it. The decision might be to contact the vendor, to void and reissue, or to leave it because the payee is still expected to cash it. The decision is not to delete the line so the difference shrinks.
The same habit applies to deposits in transit. A deposit we recorded and the bank has not shown yet stays on the list for a short time. If it never arrives, it was not a deposit. We reverse it in the month we learn that, and we say so.
The work is ordinary. It takes the statement, the register, and a willingness to leave the month open until those two agree.
The chart has to be readable in the spring
Unfold this part
A chart of accounts is the set of names the year will be told in. If those names change every few weeks, or if half the spending sits in one bucket called other, the person preparing the return is starting over. Mapping the names to the lines a return can use is part of the close, not a surprise in March.
We keep the working list short. Names nobody has used are archived so the history remains and the day-to-day list does not scroll forever. We do not delete a name that still holds a balance. Archiving is for names that are empty and finished.
New names get a plain description. Supplies means supplies. A name that tries to hold three ideas will be split the first month we see it used that way. The return cannot guess which third belonged where.
Fixed assets, payroll items, and money owed to contractors each keep their own list under the chart. A single expense line that tries to stand in for all three will not survive a notice. The sublists are how we answer.
A household bill is split before it is entered
Unfold this part
Some costs serve the work and the home at the same time. Power for a room used as the shop, a phone plan with one line for customers and one line for the family, a card that buys both. The bill arrives as one number. The company is not allowed to absorb that entire bill.
The useful question is how much of that bill the shop actually consumed. Only that portion can sit with the company. The remainder stays personal. The original phone line into a house, the one that never calls a customer, stays personal too. Putting the full household electric bill on the company, while also claiming a home-office share somewhere else, counts the same dollars twice. We pick one treatment and write it down.
The test is the same in every state because it is a federal habit, not a local one. These pages refuse to publish a made-up percentage. On a real file the share comes from how the room or the line was actually used, and it is written in the workpapers for that year.
If you cannot describe the share, the cost stays off until you can. A guessed percentage is a number we will not defend.
What these pages will not promise
Unfold this part
We will not promise a refund, a savings figure, or a rank against another firm. We will not say the month is closed when the difference is not zero. Running payday is outside this practice. Signing an audit, a review, or a compilation sits outside it as well.
We will say what the file shows. If the open item is a missing statement, we will ask for the statement. If the open item is a report that needs another firm, we will say that on the first call, before a letter is drafted.
The pictures on this site are people doing the work, not a chart of totals. No client name is written on them, and none of them is a skyline. No stock-model portrait is on these pages. The who card carries a closed binder with a gold tab, drawn for this page, with no name and no address.
The pictures of the work are people at the books: a bookkeeping table, a ledger room, files being sorted, and a room working a stack of pages. The three office photographs on the home are documentary scenes. Credits for each file sit on the credits page, not in this offer. The books page uses one more documentary room. It is not a scanned tax form.
Each of those photographs is one file, used once, of people doing the month rather than a chart that pretends the month already agreed. The adding machine, the employee list, and the calendar on the wall stay on the home and nowhere else. A visitor can tell the work from the picture before reading the sentence under it. We would rather show that room than a pale grid with a number in the corner. Bring the statement that still disagrees. The form asks for that month and a phone number, and the call starts from the page you are holding.
Bring the month that is stuck. The form takes the month you name and a phone number so the practice can call about that month. That is enough to start.
Bring the open month
Bring the open month
You will be talking to the Steven Palmieri practice.